
Colorado Wildfire and Insurance Realities: What Buyers Need to Know Before They Fall in Love with a House
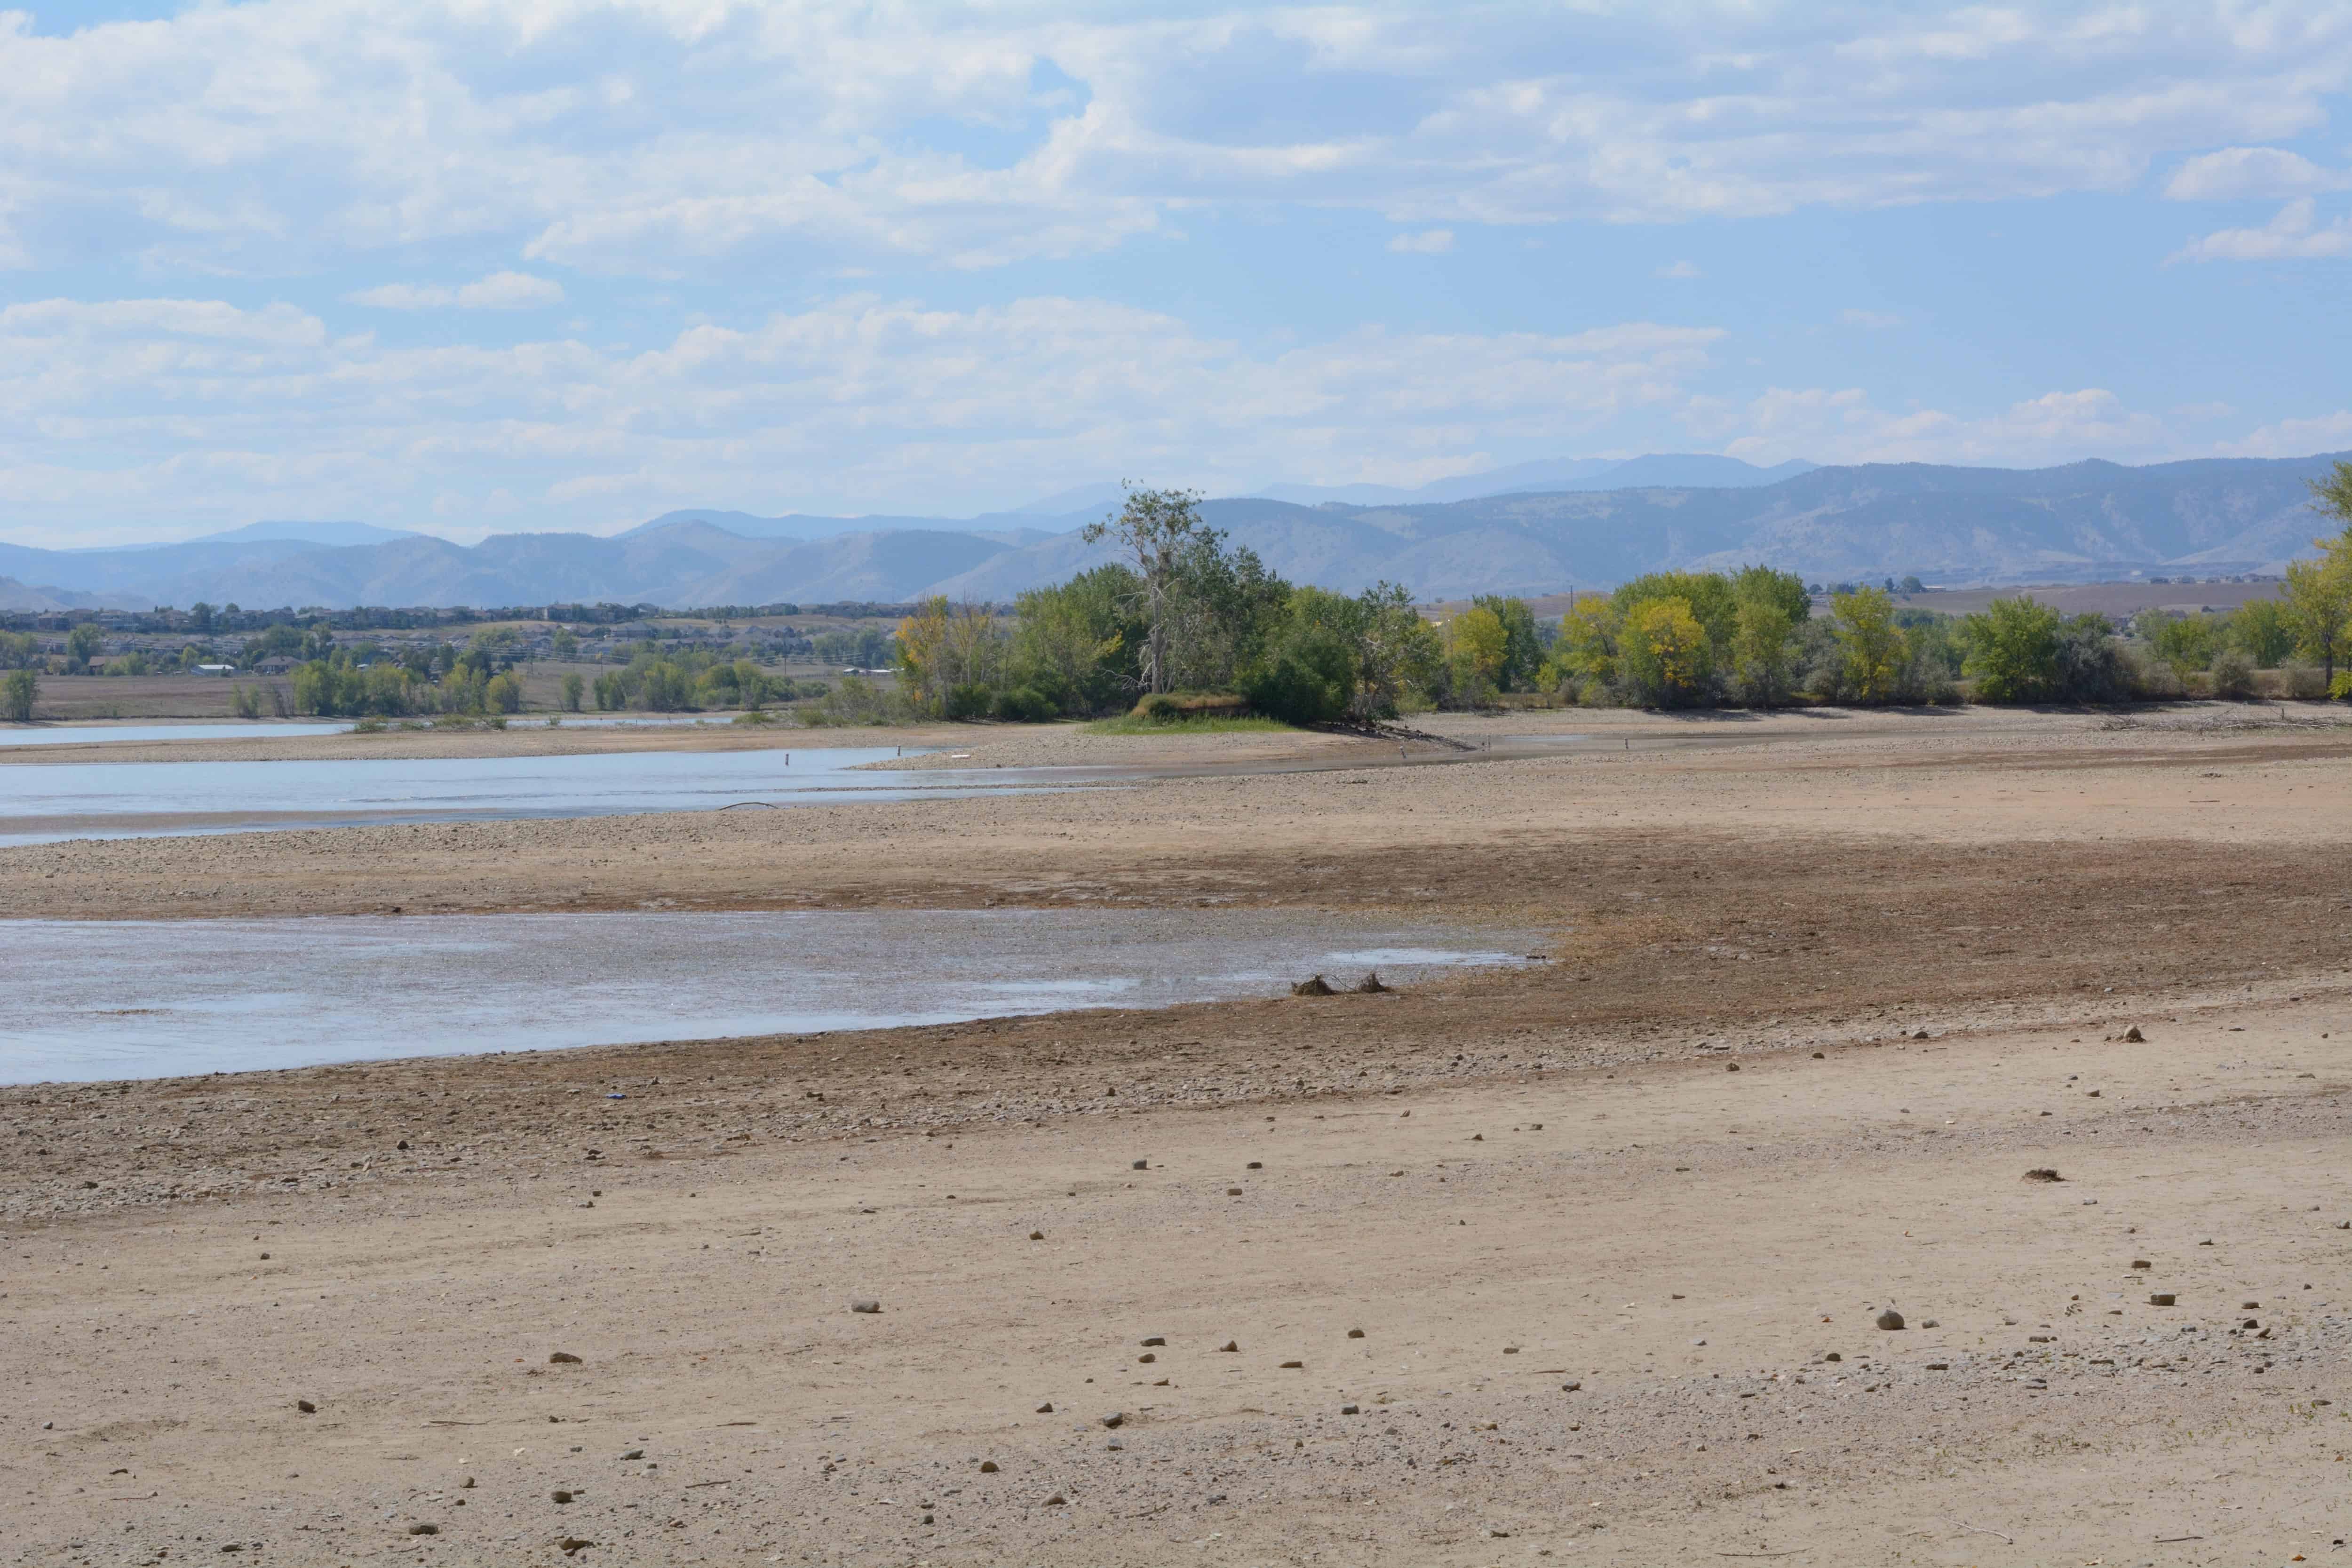
Photo by Abhi Verma on Unsplash
Insurance has quietly become one of the things that can derail a Denver home purchase, and most buyers don't think about it until the week of closing. By then, you're already emotionally attached to the house. I'd rather have this conversation with you earlier than that.
It's Not Always the Fire You'd Expect
Everyone assumes wildfire is the main driver of Colorado's rising insurance costs, and in the foothills and mountain corridor, it genuinely is. But inside Denver County itself, state data actually points somewhere else. Hail, not wildfire, is the biggest single factor in most Front Range premiums, in some counties accounting for around half the total cost. Wildfire's share of a typical Denver County premium is small by comparison.
That doesn't mean wildfire risk is irrelevant if you're looking at a property in the foothills, Evergreen, or anywhere along the wildland urban interface. It means the story is different depending on where in the metro you're actually buying, and it's worth asking your insurance agent directly which risk is driving your specific quote rather than assuming.
Photo by Luke Southern on Unsplash
What Changed This Year
A new state law took effect July 1, 2026, that gives Colorado homeowners a right they didn't have before: the ability to see and challenge the wildfire risk score an insurer uses to price or deny your policy. For years, carriers used proprietary models to score properties with no requirement to explain the number or let a homeowner push back on it. That's changed now, and if you get a nonrenewal or a steep increase tied to a wildfire score, you have real recourse.
The state has also stood up a grant program aimed at helping homeowners fortify roofs against hail, since that's the bigger cost driver here. It's still being built out, but it's worth watching if your roof is getting older.
For homes that genuinely can't find coverage through the regular market, Colorado's FAIR Plan exists as a backstop. It's worth knowing that it caps coverage at $750,000 and pays out based on actual cash value rather than full replacement cost, which in a lot of Denver metro price points wouldn't come close to covering a full rebuild. It's a safety net, not a substitute for standard coverage.
Photo by Vitaly Gariev on Unsplash
What This Means While You're Shopping
Colorado premiums overall have more than doubled since 2019, and that's simply part of the cost of owning here now. Most homeowners statewide are now looking at somewhere in the $4,000 to $5,000 range annually, with high-risk zones running well above that. My advice to buyers is the same thing I'd want to know myself: get an actual insurance quote on a specific property before you're deep into a contract, not after. A house that looks affordable on paper can carry a very different monthly number once insurance is added in, especially anything near open space, with an older roof, or in a higher-risk zip code.
If you're selling a home with an older roof, this is also worth thinking about from your side. A recent roof replacement or documented mitigation work can be a genuine selling point right now, not just a maintenance item.
The Bottom Line
Insurance isn't a box to check the week before closing anymore. It's a real cost that deserves attention early, whether you're buying or getting ready to list. I'm glad to connect you with agents who can get you a real quote before you're too far in to walk away comfortably.
Brian Trampler is a Denver native and Broker Associate with Corcoran Perry & Co. He holds the Pricing Strategy Advisor (PSA) designation and helps buyers and sellers work through real decisions across the Denver metro and Front Range.
Before real estate, Brian spent over 20 years in IT product management and product marketing, work built on solving real problems with clear information. He brings that same approach to real estate: straight answers, no sales pitch, and a willingness to walk through the details most agents skip.
If something in here raised a question about your situation, I'm happy to talk it through. No agenda — just a straight conversation.
Have a question about your own situation? Send Brian a message, call 303.638.1633, or email btrampler@corcoranperry.com.
#PerformYourMove



Socials